
Know Your Customer (KYC) In Digitized Banking - PT 2
Digitized KYC enhances speed, accuracy, compliance, and customer experience. Learn the benefits, best practices, and implementation steps.
Know Your Customer (KYC) In Digitized Banking - PT 2
Traditional Know Your Customer (KYC) processes, once considered as the foundation of compliance in banking, have now become a major hurdle to gaining higher customer acquisition and efficiency in operations. Although it served its purpose in an era of branch-based banking and paper-based documentation, the traditional mode of KYC process has become increasingly inadequate to meet expectations of present-day customers who demand instant, seamless, and secure financial services.
Digitized KYC is indeed a complete paradigm shift in how financial institutions approach customer onboarding, risk assessment, and regulatory compliance. Banks and other financial institutions that have implemented detailed digital KYC solutions have positioned themselves to capture greater market share, reduce operational costs, improve regulatory compliance, and build stronger customer relationships. Let’s quickly delve into the benefits of adopting a digitized KYC approach, best practices and implementation of the same.
Benefits of Digitized KYC for Banks and Customers
Firstly, traditional KYC processes that might require 5-10 business days and involve different manual steps in the review procedure can be completed within minutes through automated digital systems, thus improving efficiency. Through this, banks can process higher volumes of applications by customers with the same or fewer members of staff at a faster rate.
The improvement in accuracy attained via digital KYC systems exceeds what human reviewers can accomplish especially when dealing with large volumes of applications. Machine learning algorithms can identify subtle patterns and inconsistencies that humans might miss while eliminating the variability and fatigue factors that affect the latter.
Ability to manage risk is further strengthened through digital KYC systems as it can check different sanctions lists, adverse media databases, registries of politically exposed persons and other risk databases in real-time, ensuring that a detailed risk assessment is carried out for all customers. Monitoring capabilities also enable proactive risk management by identifying emerging risks or a change in customer’s circumstances that might require adjustment of the portfolio or higher monitoring procedures.
Scalability is another important advantage of digital KYC systems, as it enables banks to grow their customer base without any proportional increase in the compliance team or operational costs. Traditional KYC processes create linear scaling challenges where each new customer requires approximately the same amount of manual effort for verification and ongoing monitoring. On the other hand, digital systems process thousands of customers with minimal increased cost which enables banks to focus on growth without compromising compliance. Furthermore, regulatory compliance is strengthened through digital systems that maintain detailed audit trails, ensure consistent application of policies and procedures, and provide real-time reporting capabilities for compliance.
Furthermore, the digital KYC process delivers amazing customer experience that directly translates into higher customer satisfaction scores, improved conversion rates, and stronger customer loyalty. Reduction in time required to open new accounts or to access financial services, with many digital processes completing verification within minutes rather than the days or weeks required by traditional approaches is a huge benefit. This improvement in speed is very valuable for younger customers who are accustomed to instant digital services in other industries and expect similar response time from financial service providers.
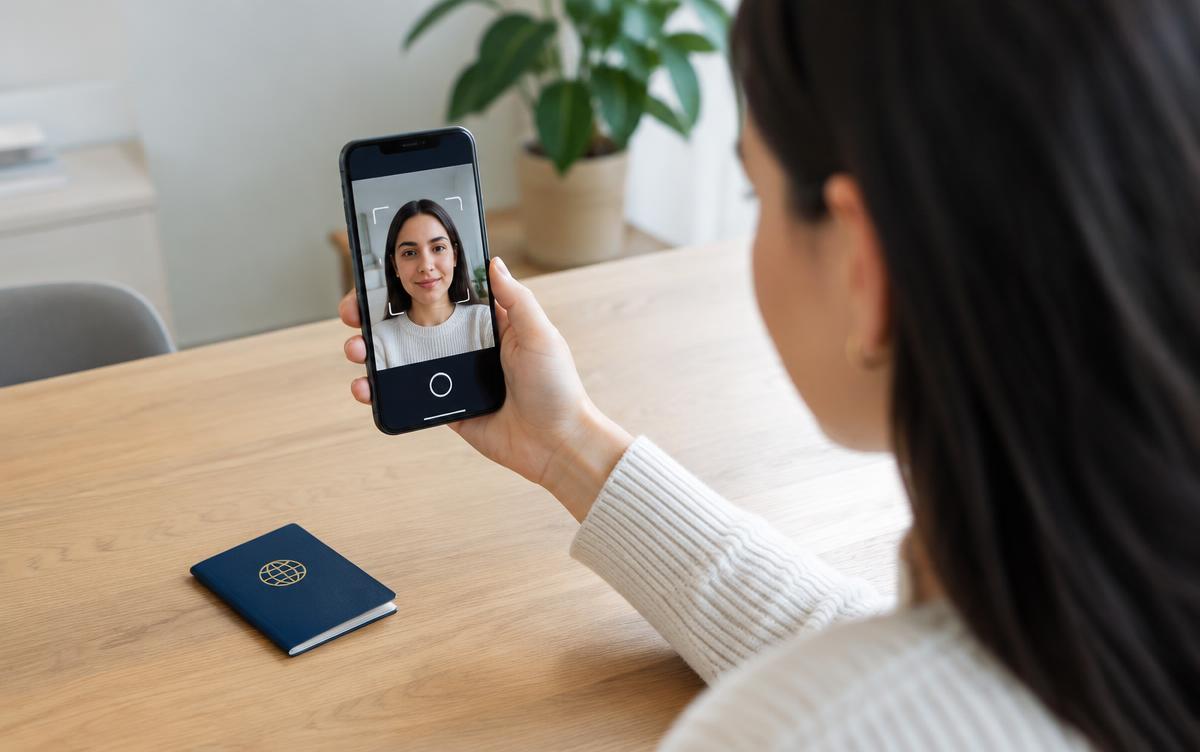
It's available 24/7, removes the need to submit documents physically, or photocopy or even send documents via postal services. Customers can simply take a photo of their identification documents using the camera app on their smartphone and advanced systems will automatically extract and verify the required information within seconds. The consistency of digital KYC processes ensures that all customers receive identical treatment regardless of which channel they used in accessing services or which members of staff might be involved in processing their applications. This consistency removes the variability that customers sometimes experience with manual processes, where different branch members of staff or processing centers might apply varying standards or require different documentation. Digital systems apply identical criteria and procedures for every customer, ensuring fair and consistent treatment while reducing confusion experienced by customers about requirements or processing standards.
Again, protection of privacy is strengthened through digital systems which minimizes the number of people who have access to sensitive information of the customers while maintaining detailed security controls throughout the verification process. On the other hand, traditional processes often involve different members of staff handling physical documents and personal information, creating numerous opportunities for unauthorized access or disclosure of information. Digital systems can restrict access to sensitive information on a need-to-know basis while maintaining detailed logs of who accessed what information and when, thus providing better privacy protection and accountability than traditional paper-based processes.
Best Practices and Implementation Outline
Banks must conduct thorough documentation of current KYC workflows, including processing times, resource requirements, error rates, level of customer satisfaction and metrics about the effectiveness with compliance. This assessment should spot pain points, inefficiencies, and opportunities to improve which digital solutions can address.
The assessment process should include detailed analysis of existing technology infrastructure to identify requirements for integration, issues of data quality and systems limitations that could affect the implementation of digital KYC. Legacy core banking systems, customer relationship management platforms, compliance monitoring tools, and data warehouses must be evaluated for their ability to support in real-time. Banks must develop comprehensive risk registers that identify specific risks, assess their probability and potential impact, and establish appropriate strategies for mitigation.
This planning should include contingency procedures for system failure, delay in obtaining regulatory approval, issues about vendors performance and challenges faced by customers in adopting the same which can affect the success of implementation or ongoing operations.
Also, stakeholder and communication planning will ensure that all relevant internal and external parties understand the objectives, timeline, and implication of implementing digital KYC. This includes leadership at the executive level, compliance teams, members of staff in operations, the tech team, customer service representatives, regulators, audit committees, and key customers who might be affected by changes in the process. Clear communication strategies will help in building the needed support for execution while managing expectations about timelines, capabilities, and potential disruptions during the time frame for transition.
In conclusion, digitized KYC processes present opportunities for banks and other financial institutions to quickly improve customer experience, enhance efficiency in operations, and strengthen regulatory compliance. Best practices and implementation outline demonstrates that successful change requires careful assessment of current capabilities, thoughtful planning for integration, detailed risk management and sustained commitment to constant improvement and optimization. It’s up to the leadership in the banking and other financial institutions to decide whether or not to adopt digitized KYC processes.
FAQ
Q1. Why is traditional KYC becoming inadequate in banking?
Traditional KYC is slow, paper-based, and labour-intensive. It delays customer onboarding, increases costs, and creates inefficiencies compared to fast, automated digital KYC solutions.
Q2. What are the key benefits of digitized KYC for banks?
Digitized KYC improves efficiency, accuracy, scalability, compliance, risk management, and customer experience. It enables instant onboarding and reduces operational costs.
Q3. How does digital KYC enhance customer experience?
Digital KYC allows customers to verify their identity within minutes using smartphones, biometrics, or online verification tools, delivering convenience, speed, and 24/7 accessibility.
Q4. What technologies are commonly used in digital KYC?
Technologies include AI, machine learning, biometrics (facial recognition, fingerprint), blockchain, and automated verification tools integrated with compliance databases.
Q5. What best practices should banks follow when implementing digital KYC?
Banks should evaluate existing workflows, assess risks, ensure data quality, plan for integration with legacy systems, train staff, and maintain transparent communication with regulators.