
KYC: How Artificial Intelligence Has Taken Customer Verification To The Next Level
Discover how AI has revolutionized KYC processes, reducing verification times from weeks to minutes while achieving 99.5% accuracy in document authentication and cutting operational costs by 40%.
KYC: How Artificial Intelligence Has Taken Customer Verification To The Next Level
A few years ago, it was a herculean task trying to carry out Know Your Customer (KYC) process which spanned from reviewing documents manually, using phone calls to verify certain information to lengthy background checks that culminated into days and sometimes even weeks. Now with technological advancement and the power of artificial intelligence (AI), financial institutions carry out the KYC process in a matter of minutes. It is wrong to think that AI systems are just for digitizing existing processes, on the contrary, they create an entirely new approach to understanding and verifying the identity of the customer.
Table of Content
- The Traditional KYC Process
- The AI KYC Process
- Document Verification and Authentication
- Identity Verification and Background Screening
- Risk Assessment and Scoring
- The Technology Behind AI-Powered KYC
- Essential AI Technologies
- Data Integration and Management
The Traditional KYC Process
The traditional KYC process uses manual verification, which creates challenges that can take as long as 5-15 business days to complete with human reviewers prone to making mistakes, one that occurs in approximately 15-20% of manual reviews. This delay impacts negatively on businesses with potential customers abandoning applications as a result of lengthy onboarding processes.
The AI KYC Process
Document Verification and Authentication
Powered by deep learning, modern optical character recognition (OCR) systems, can instantly extract and verify information from identity documents with 99.5% accuracy which with certitude totally exceeds human performance. These systems don't only read text, they analyze document structure, security features, fonts, and formatting to spot any form of high-end forgery.
Computer vision algorithms can also detect any attempt to tamper with a document which human reviewers would not have been aware off. For instance, AI can identify when photos have been digitally altered, text has been overlaid on existing documents, or when documents have been created using templates rather than issued by legitimate authorities. In fact, advanced systems can analyze micro-features like paper texture, ink patterns, and security holographs which the human eye can't detect.
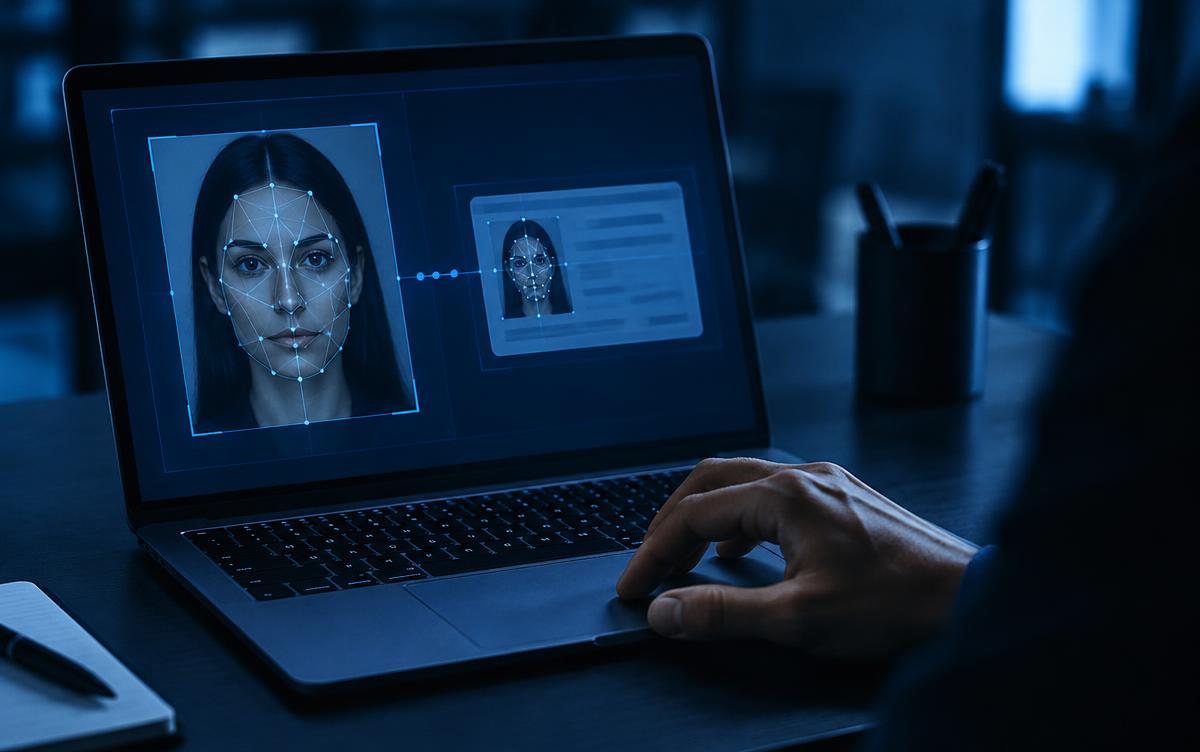
Then again, real-time biometric matching has gone past photo comparison which is typically carried out by humans. Modern systems use facial recognition algorithms that can verify the person's identity even when photos were taken years apart, irrespective of aging, weight changes, and different lighting conditions. There's something called liveness detection, which prevents fraud attempts using photographs or videos, by analyzing micro-movements, skin texture, and other biological indicators that confirm a live person is present.
HSBC, J.P. Morgan, TSB, Bunq, Doha, First Abu Dhabi Bank and other financial institutions and digital banks such as Bankinter (Spain), N26 (Berlin), LHV (Estonia), Starling Bank (UK) among others, have embraced the use of AI. Imagine having an AI-powered document verification system that reduces processing time from 5 days to 5 minutes and can automatically extract data from over one hundred and fifty document types across various countries, cross-reference information against multiple databases, and flag potential issues for human review, all in real-time as customers upload documents via mobile apps.
JPMorgan Chase implemented an AI-powered KYC system that reduced customer onboarding time by 90%. It automates data collection, identity verification, and risk assessment, which has made its KYC workflow faster. It lowered operational expenditures by up to 40% compared to traditional methods. This definitely changes everything, making operations seamless and efficient.
Identity Verification and Background Screening
When it comes to pattern recognition in customer data, identifying connections and irregularities that humans might miss, machine learning algorithms excel in this area. These systems analyze hundreds of data points at the same time from device fingerprints and behavioural patterns to social media footprints and transaction histories, thus creating comprehensive identity profiles that are way better than the traditional verification method.
Modern Natural Language Processing (NLP) algorithms understand context, can detect sentiment, and distinguish different individuals with similar names. For instance, it can differentiate between negative news about 'James Parker the music artiste' versus 'James Parker the author' by analyzing contextual clues, dates, locations, and associated entities mentioned in articles.
Automated Politically Exposed Person (PEP) and sanctions list checking now happens in real-time rather than periodically. AI systems monitor global databases continually, and automatically update risk profiles when new sanctions are imposed or when the individual's political status changes. These systems can even identify indirect connections, for example, flagging a family member of a sanctioned individual even if they were not named on the sanctions list(s).
When it comes to behavioural biometrics, AI continuously authenticates users based on their 'unique behavioural patterns', for instance, an individual's mobile device usage habits, and even walking patterns when using mobile devices. This creates a 'behavioural fingerprint' that's very difficult to imitate and provides ongoing authentication throughout the customer relationship.
Risk Assessment and Scoring
Unlike traditional systems that apply static criteria, AI models continuously learn and adjust risk scores based on new data patterns. For instance, a customer's risk score might decrease after recording steady legitimate transaction patterns, or rise if their behaviour suddenly changes or if they're associated with high-risk entities that have been newly identified.
When it comes to real-time transaction monitoring, the use of machine learning models can spot suspicious patterns across millions of transactions at the same time. These systems identify irregularities not just in individual transactions, but in complex networks of related transactions that cuts across multiple accounts, institutions, and time periods. For instance, AI can detect layering schemes where funds move through multiple accounts in rapid succession to obscure their origin.
Also, anomaly detection algorithms can identify suspicious activities by understanding normal patterns for different customer segments and flagging deviations that warrant investigation. The system might detect that a customer who typically makes local retail purchases, has suddenly initiated a large international wire transfer, or that the login patterns has changed significantly. Unlike traditional based systems that rely on predetermined thresholds, AI systems understand that what's normal varies significantly between different customer types and contexts.
A customer who demonstrates consistent, legitimate behaviour patterns might qualify for reduced monitoring and faster transaction processing, while unusual patterns trigger enhanced scrutiny. This approach reduces false positives while improving detection of genuine risks.
The Technology Behind AI-Powered KYC
Essential AI Technologies
Firstly, machine Learning and Deep Learning form the basis of contemporary KYC systems. Supervised learning algorithms are trained on vast datasets of both known legitimate and fraudulent cases, thus, learning to identify patterns that indicate risk. Unsupervised learning techniques spot previously unknown fraud patterns by identifying anomalies in data that don't match any established categories. Deep learning neural networks can process complex, multi-dimensional data like images, text, and behavioural patterns at the same time.
Secondly, Natural language Processing (NLP) enables systems to understand and analyze text-based information at scale. Advanced NLP models can read and even understand legal documents, news articles, court filings, and regulatory announcements in multiple languages. It can extract relevant information, understand context, and identify relationships between entities mentioned across different documents and time periods.
Thirdly, computer vision technology processes visual information from identity documents, facial photos, and even video verification sessions. Modern systems can detect document security features, verify photo authenticity, and perform facial recognition with accuracy that exceeds human capabilities. They can also analyze video feeds in real-time to detect deepfakes.
Fourthly, Robotic Process Automation (RPA) orchestrates complex KYC workflows, integrating data from different sources and routing cases for appropriate processing. RPA systems can automatically gather information from various databases, generate reports, update customer records, and even communicate with customers about status updates, while maintaining detailed audit trails for regulatory compliance.
Data Integration and Management
API enables seamless data flow between different systems, databases, and external data sources. Modern KYC platforms can instantly access credit bureaus, sanctions databases, corporate registries, and other verification sources through standardized APIs. This removes manual data entry and enables real-time verification against authoritative sources. Cloud-based infrastructure provides the scalability needed to handle varying volumes of KYC checks efficiently. Cloud platforms can automatically scale processing resources during peak periods, such as when a fintech launches a new product and scales down during quieter periods to control costs.
The Blockchain integration creates incontrovertible audit trails that satisfy regulatory requirements while enabling secure data sharing between institutions. Some implementations use blockchain to create decentralized identity verification networks where customers can reuse verified credentials across multiple service providers without repeating the entire KYC process. Also, real-time data feeds from multiple verification sources, ensure risk assessment reflects the most current information available. This includes live feeds from sanctions databases, PEP lists, adverse media monitoring services, and fraud intelligence networks that share information about emerging threats across the industry.
In conclusion, what once required days into weeks of manual labour which resulted in significant rate of customer abandonment, can now be accomplished in minutes and with mind blowing accuracy via AI. 90% reduction in onboarding time, 99.5% document verification accuracy, and up to 40% lower operational costs, the use of AI in KYC process can't be shelved. For financial institutions, this translates to having the competitive advantage, complying with regulations and saving substantial cost that can be reinvested into innovation and customer service. As fraudsters become more sophisticated and devious in their ways and regulatory requirements continue to increase, AI systems are essential for creating and maintaining a seamless tripartite experience from KYC compliance, to security and greater customer experience.
Learn about KYC today and how to climb the career ladder successfully. Enrol now on titanscareers.com
Frequently Asked Questions
How long does AI-powered KYC take compared to traditional methods? AI-powered KYC systems can complete customer verification in 2-5 minutes, compared to traditional methods that take 5-15 business days. For example, JPMorgan Chase reduced their customer onboarding time by 90% after implementing AI-powered KYC systems.
What is the accuracy rate of AI document verification? Modern AI-powered OCR systems achieve 99.5% accuracy in document verification, significantly exceeding human performance. These systems can analyze document structure, security features, fonts, and formatting to detect sophisticated forgeries that human reviewers might miss.
How does AI reduce KYC compliance costs? AI reduces KYC costs by up to 40% compared to traditional methods. This is achieved through automation of manual processes, reduction in false positive rates from 95% to less than 5%, and elimination of lengthy manual review processes that previously required multiple staff members.
Is AI-powered KYC secure and compliant with regulations? Yes, AI-powered KYC systems are designed with robust security measures including encryption, blockchain integration for audit trails, and compliance with global regulations like AML and CFT requirements. The systems provide comprehensive audit trails that satisfy regulatory requirements.
Can AI detect deepfakes and sophisticated document forgeries? Advanced AI systems can detect deepfakes and document tampering through computer vision algorithms that analyze micro-features like paper texture, ink patterns, security holographs, and biological indicators that are invisible to the human eye. Liveness detection prevents fraud attempts using photographs or videos.
How does behavioural biometrics work in KYC processes? Behavioural biometrics creates a unique 'behavioural fingerprint' by analyzing patterns such as typing rhythm, mouse movements, mobile device usage habits, and even walking patterns. This provides ongoing authentication throughout the customer relationship and is extremely difficult to replicate.
What is the difference between false positives and false negatives in KYC? False positives occur when legitimate customers are incorrectly flagged as suspicious (traditional systems: 95%, AI systems: <5%). False negatives happen when genuinely suspicious customers pass through undetected (traditional: 10-15%, AI: 1-3%). AI significantly improves both rates.
How does AI help with ongoing customer monitoring after initial verification? AI systems provide continuous monitoring by analyzing transaction patterns, updating risk scores based on new data, monitoring sanctions lists in real-time, and detecting behavioural anomalies that might indicate fraud or money laundering activities.
How do AI systems ensure data privacy and GDPR compliance? AI-powered KYC systems implement data minimization principles, encryption for all data transmission, secure multi-party computation for sensitive data processing, and 'right to be forgotten' capabilities. Federated learning allows institutions to improve AI models without sharing sensitive customer data.